Plain-English guides, tools and answers so you can make confident decisions about buying, refinancing and building wealth through real estate.
Never A No
Working for a company that’s all about finding mortgage solutions and never saying “no” is a truly uplifting experience. We thrive on thinking creatively and breaking away from the traditional norms of the mortgage process. Our commitment to problem-solving means we see challenges as opportunities to come up with innovative solutions.
Relationships Are Everything
Realtors and loan officers working closely together is a big deal. They’re the dynamic duo that makes buying a home smoother and more enjoyable. This partnership leads to quicker, more efficient transactions and ensures any bumps in the road are smoothed out. It’s all about trust and teamwork.
No Shortcuts
Mortgages involve money and complex processes, so it’s vital to be thorough and accurate. Taking shortcuts can lead to mistakes that hurt borrowers and lenders alike. At The Heichel Team, we do things properly so everyone involved can feel secure and confident about the mortgage process.
In the competitive 2026 housing market, many buyers in Rochester and Austin, Minnesota, are finding that the “perfect” home doesn’t exist on the shelf. A renovation loan finances both the purchase and the personality of a home in a single mortgage.
Explore how VA home loans work and why they’re one of the most flexible options available to veterans. Learn about zero-down benefits, no PMI, renovation loan options, and how VA financing can help you compete and build the home you want.
Looking to build long-term income through rental property? Learn how investment property loans and DSCR financing work, how rental income impacts qualification, and what investors should consider when structuring financing for portfolio growth.
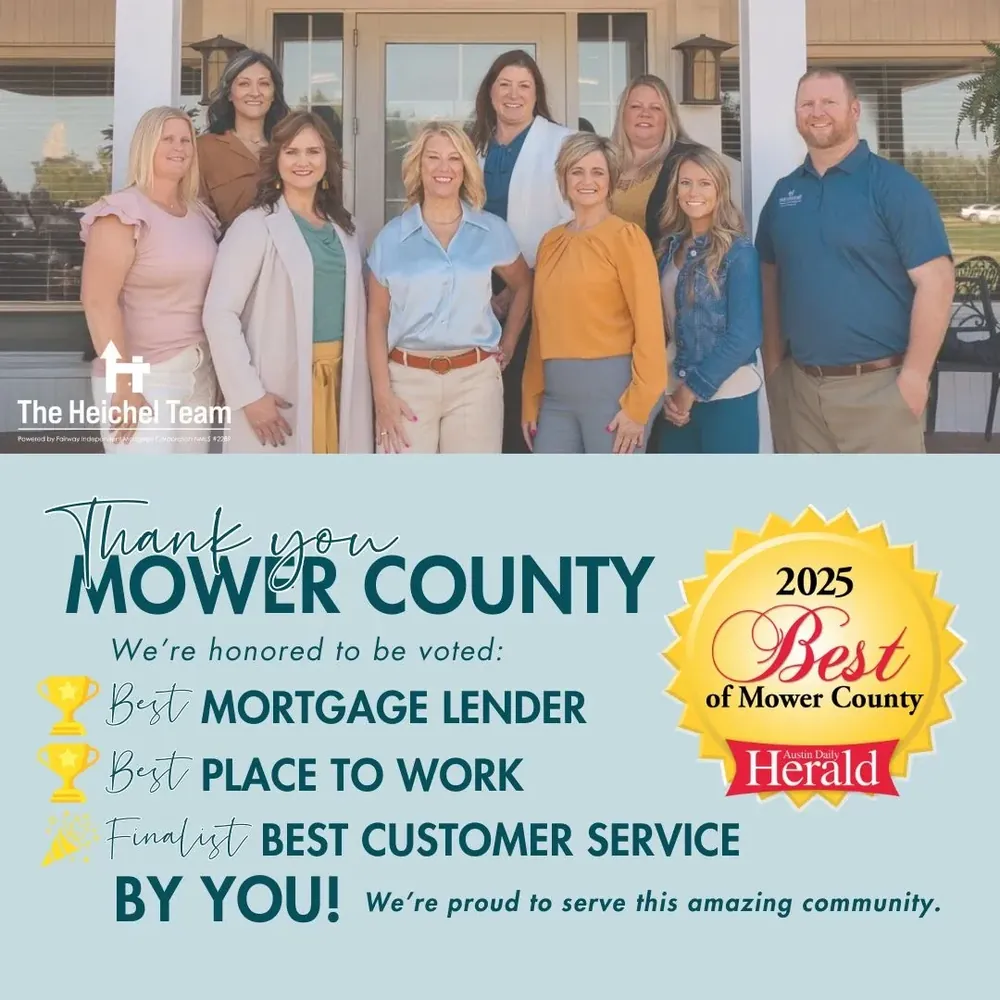
The Heichel Team was voted Best Mortgage Lender and Best Place to Work in the 2025 Best of Mower County awards, and named a finalist for Best Customer Service.
Navigating the home-buying process for the first time can be overwhelming. Here are some essential tips to get you started on the right foot.
1. Start by setting a budget
Before you fall in love with a home, know what you can realistically afford. Factor in your down payment, monthly payments and lifestyle. A clear budget keeps your search focused and stress-free.
2. Get pre-approved for a mortgage
Pre-approval isn’t just a formality; it’s your first step to becoming a serious buyer. It shows sellers you’re ready and gives you a clear picture of your loan options and price range.
3. Research neighborhoods
Take time to explore different areas, commute times, school ratings and local amenities to make sure the neighborhood fits your lifestyle.
4. Work with a real estate agent
A great agent is your guide, advocate and negotiator. They know the market, help you avoid costly mistakes, and make the process smoother from start to finish.
Qualifying for a loan depends on several factors including your credit score, income, employment history and debt-to-income ratio. We evaluate these factors to determine your eligibility and the best loan options for you.
How can I improve my chances of getting approved for a loan?
Improving your credit score, reducing existing debts and ensuring a stable income can enhance your loan approval chances. The best way to set yourself up for success is to get pre-approved early so we can look at your situation and give you a plan custom fit to your needs.
Do I need 20% down to buy a home?
No, you do not need 20% down to buy a home. There are loan programs that allow lower down payments, even as little as 3% down for qualified buyers. When you put less than 20% down you will have PMI (private mortgage insurance). PMI is a useful tool for homebuyers and is not something to be afraid of.
Can I get a loan if I have low credit?
Yes, it’s possible to get a loan with low credit, though the options and interest rates may vary compared to those with higher credit scores. We offer a range of products for different credit profiles and can provide guidance on how to improve your credit to qualify for better terms.
What is PMI, and is it bad?
PMI, or private mortgage insurance, is insurance lenders require from borrowers who put down less than 20% on a conventional loan. It protects the lender in case of default. PMI is not a bad thing; it’s a powerful homebuying tool. With decent credit, PMI can be inexpensive and it lets buyers purchase without a 20% down payment.
Awards & Recognition
Named to the Scotsman Guide Top Originators list
President’s Club and Chairman’s Club recognition
Voted “Best Mortgage Lender” – Best of Mower County
Five Star Mortgage Professional recognition
Experience & Expertise
20+ years in mortgage lending
Specialized in helping first-time homebuyers
VA loan expert serving military families
Reverse mortgage specialist helping retirees
Certified Divorce Lending Professional (CDLP)
Customer Service
4.86-star average review rating
1,395+ client reviews across Google, Zillow, Facebook and Experience.com
Satisfaction scores above company averages
Repeat and referral rates above industry benchmarks
Community Involvement
Partnered with local housing nonprofits
First-time homebuyer education workshops
Supported veteran housing initiatives
Active in local chambers of commerce and real estate associations